Greek homebuyers: an ECB rate hold is not your mortgage offer
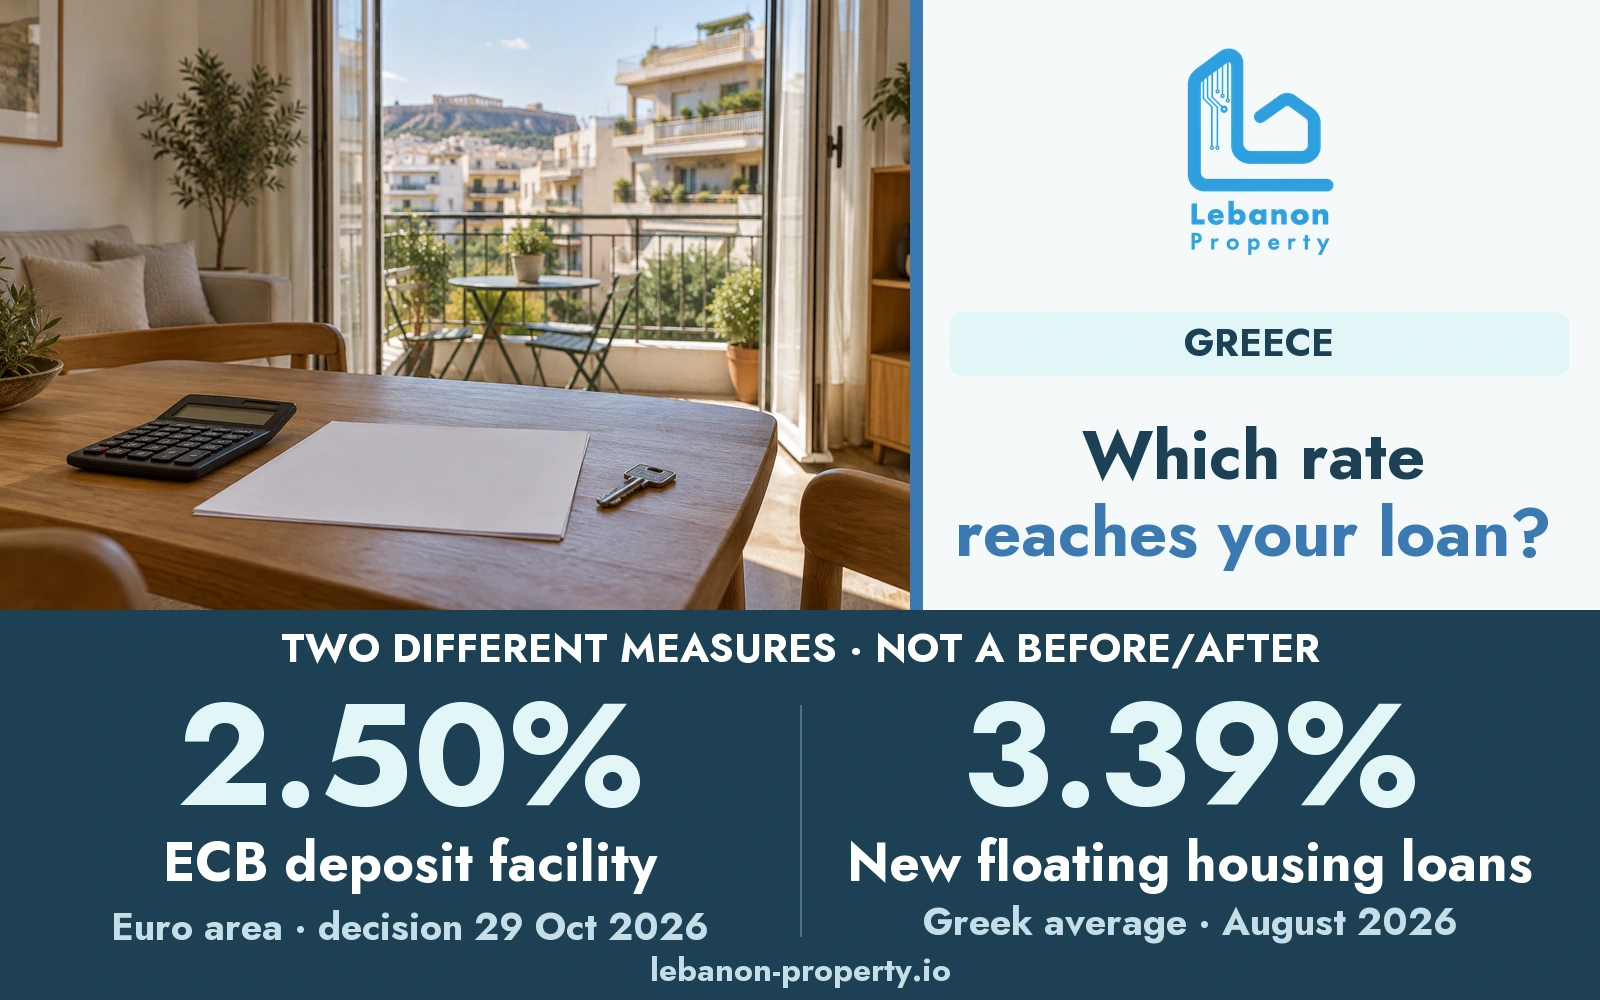
AI-generated illustration. Editorial apartment scene, not a listing or bank offer. The figures describe different rates and periods; neither is a personal mortgage quotation.
The ECB decision and Greece’s housing-loan average measure different things. Here is how to use them without mistaking either for a personal borrowing rate.
A central-bank headline can change the questions a buyer asks, but it does not replace a written loan offer. If you are comparing a home in Greece with your available budget, start by separating monetary policy, published banking averages and the terms a lender will actually offer you.
The current policy decision
On 29 October 2026, the European Central Bank held its key rates unchanged, including the 2.50% deposit-facility rate. It did not commit to a future rate path. That rate is a euro-area policy instrument, not the price of a Greek household mortgage.
European Central Bank · 2026-10-29
What the Greek mortgage figure measures
The Bank of Greece’s release of 1 October reports a 3.39% average for new floating-rate housing loans in August 2026. The category includes initial rate fixation up to one year; new business means agreed contracts, not disbursements. This earlier average is neither an October quote nor directly comparable to the ECB deposit rate.
Bank of Greece · 2026-10-01
Ask for terms you can put into a household budget
A lender’s written offer should allow you to see what is fixed, what may change and when. Compare like-for-like borrowing amounts and terms rather than choosing the lowest prominently advertised percentage.
- Identify whether the rate is fixed or variable and, if variable, the reference rate, margin and reset dates.
- Request the payment schedule, applicable fees, insurance requirements and total borrowing-cost disclosure.
- Ask how payments would change under a higher-rate scenario, using the actual offer terms rather than a forecast.
- Keep purchase costs, repairs and an emergency reserve separate from the deposit and monthly instalment.
Link the financing decision to the property
The affordable purchase price depends on more than an average interest rate. A home requiring immediate works creates a different cash requirement from one ready to occupy. Our guide to construction quotations in Greece can help you organise that part of the comparison.
The practical next step is a current written offer and a complete property budget reviewed with your lender and relevant advisers. A policy hold does not guarantee a cheaper future mortgage or a rise in the home’s value.
Prepared by Lebanon Property on 31 October 2026. Source dates and data periods are stated above. Practical implications are editorial analysis, not a valuation, individual legal or credit advice, or a guarantee of prices or returns.
Sources
- Monetary policy decisions — 29 October 2026
European Central Bank · Published: 2026-10-29 · Accessed: 2026-10-31
29 October 2026 policy decision; rates held unchanged · Euro area policy rates, not Greek retail mortgage offers
- Interest Rates on Bank Deposits and Loans: August 2026
Bank of Greece · Published: 2026-10-01 · Accessed: 2026-10-31
August 2026 new housing-loan contracts · Greek euro-denominated new housing loans at floating rates, including initial fixation up to one year; average, not individual quote
That’s a wrap.
2 min well spent.
Useful? Send it to someone who’s house hunting.
Ready to see homes like these?
Browse verified listings, or ask our team anything on WhatsApp.